Insurance Guide for College Students: 10 Essentials on a Budget
Insurance for college students feels like an adult problem you shouldn’t have yet, but campus life is full of risks that don’t care about your age. Stolen laptops, ER visits, fender benders: they happen to students constantly. These ten budget-friendly essentials keep you protected without wrecking your ramen budget.
1. Stay on Your Parents’ Health Plan
Current law lets you stay on a parent’s health insurance until your 26th birthday, regardless of student status or where you live. This is free coverage, so use it shamelessly.
Confirm the plan has in-network doctors near your campus, since out-of-area networks can be thin. If the network doesn’t reach your college town, the university health plan becomes your backup. Never let this coverage lapse between semesters.
2. Check Your University’s Health Plan
Most universities offer student health plans, sometimes automatically billed unless you waive them. They’re designed for campus life with the health center as your home base.
Compare the university plan against staying on a parent’s policy before waiving anything. Sometimes the school plan is cheaper with better local access. Waive it only when you’re certain the alternative is solid.
3. Get Renters Insurance for Your Place
Dorm or off-campus apartment, your stuff isn’t covered by the university or your landlord. Laptops, bikes, textbooks, and clothes add up to thousands fast.
Renters insurance costs about $15 a month, often less with student discounts, and covers theft, fire, and even liability if a guest gets hurt. Photograph your belongings at move-in. It’s the cheapest adulting win available.
4. Sort Out Car Insurance Smartly
Bringing a car to campus? Your parents’ policy usually still covers you, but tell the insurer about the new garaging address. Rates change by location, and hiding it can void claims.
No car? A non-owner policy is dirt cheap and keeps your insurance history continuous for later. Good student discounts up to 25 percent reward that B average. Every option beats an uninsured accident.
5. Know What Campus Coverage Misses
Universities carry liability insurance for themselves, not for you. If you injure someone in an intramural game or damage dorm property, that’s on you personally.
Your renters policy’s liability portion and any umbrella coverage fill these gaps quietly. Read what the school actually covers before assuming you’re protected. Assumptions are expensive in campus incidents.
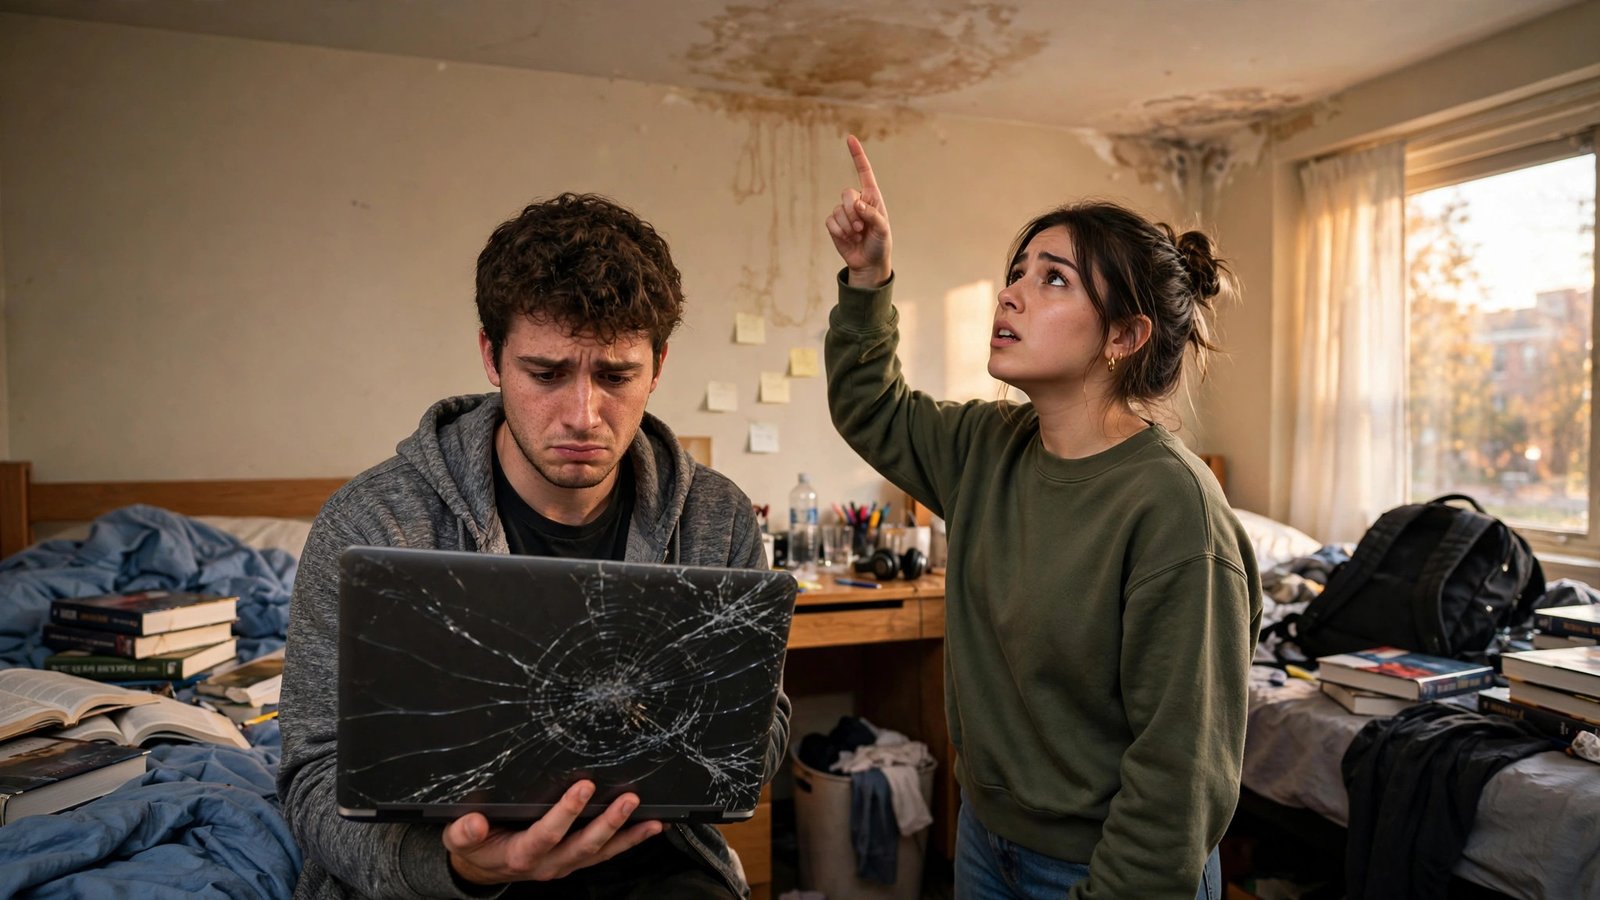
6. Insure Your Tech Properly
Your laptop is your classroom, library, and social life in one $1,200 package. Phone, tablet, and headphones push your portable tech value even higher.
Renters insurance covers these against theft and damage, usually with a deductible. For brand-new expensive gear, a scheduled personal property endorsement covers full value cheaply. Back up everything to the cloud regardless, since data isn’t insurable.
7. Get Travel Insurance for Study Abroad
Studying overseas is amazing until you need a doctor in a country where your health plan doesn’t work. Emergency medical and evacuation coverage become essential, not optional.
Many programs require proof of international coverage before you board the plane. A semester-long travel medical policy is surprisingly affordable. Don’t rely on hope and ibuprofen in a foreign healthcare system.
8. Understand Your Liability Exposure
Throwing a party where someone gets hurt, accidentally flooding the apartment below, your dog nipping a visitor: student life creates real liability.
Renters insurance includes $100,000 in liability coverage standard, which handles most student-scale incidents. Think before hosting risky events, and know your coverage exists. Adult consequences arrive earlier than expected.
9. Use the Campus Health Center First
Most universities run health centers with free or nearly free basic care for enrolled students. Colds, sprains, vaccinations, and mental health counseling often cost little or nothing.
Learn the health center’s hours and services during orientation week. It’s your front line before insurance even enters the picture. Smart students treat it as their primary care home base.
10. Budget for Premiums Like a Bill
Insurance only works if you keep paying it, so treat premiums like rent: non-negotiable monthly bills. A lapsed policy helps nobody and restarts your continuous coverage record.
Annual payment often saves installment fees if you can swing it from savings or financial aid refunds. Build the $15 to $30 monthly cost into your semester budget from day one. Protected and budgeted beats sorry and broke.
FAQs
Do college students really need renters insurance?
Yes. Neither the university nor your landlord covers your belongings, and campus theft is extremely common. At roughly $15 a month with liability coverage included, it’s the best value in student insurance. One stolen laptop justifies years of premiums.
Can I stay on my parents’ car insurance while in college?
Usually yes, but you must tell the insurer about the car’s new location. Premiums adjust by garaging address, and some companies offer distant-student discounts if you’re 100+ miles away without a car. Honesty about location keeps claims valid.
What health insurance options do college students have?
Parent’s plan until 26, the university’s student health plan, marketplace plans with subsidies if independent, or Medicaid if income qualifies. Most students use the first two. Compare networks near campus before choosing, since local access matters most.
Does financial aid cover insurance costs?
Sometimes indirectly. University health plan premiums can be included in cost-of-attendance calculations that financial aid covers. Standalone renters or auto insurance generally isn’t covered, so budget those separately. Ask the financial aid office what’s included in your specific package.
What if I’m an international student?
Most universities require international students to carry compliant health insurance, often through the school’s plan. Verify it meets visa requirements before waiving anything. Also get renters insurance for your belongings, since you’re far from any family safety net.
Conclusion
Insurance for college students isn’t about being paranoid, it’s about being prepared on a budget. Get the health, renters, and auto basics sorted this semester. Which one are you missing?